
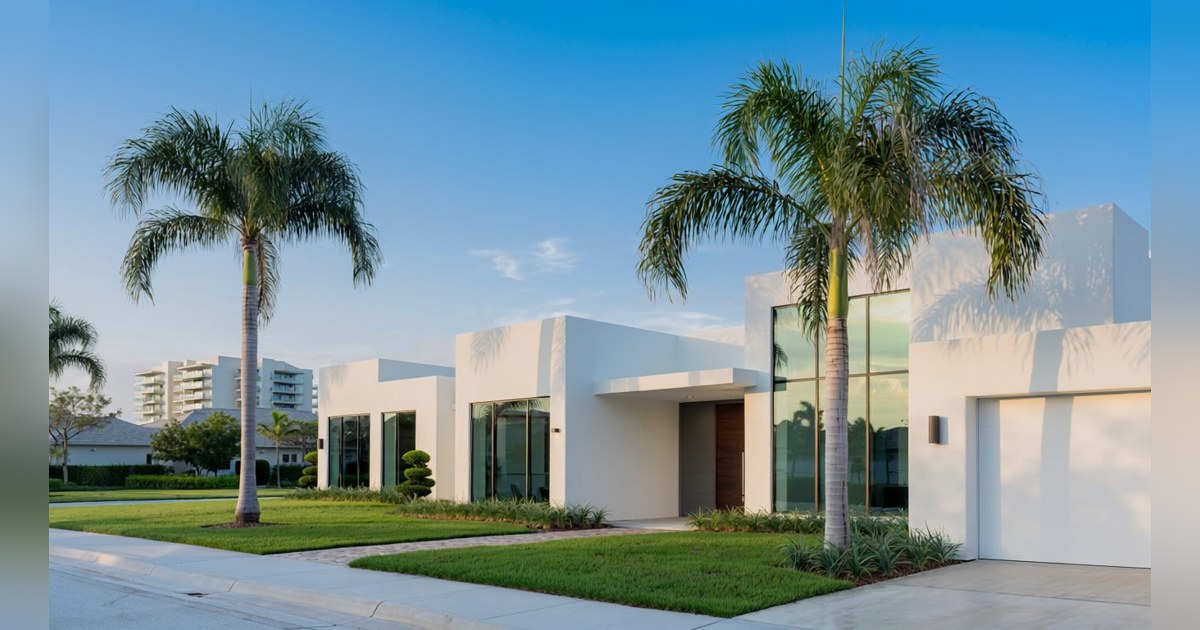
The housing market in Palm Beach County is not crashing but splitting into two distinct segments, according to real estate agent Loodmy Jacques, who leads The Jacques Team at Keller Williams Reserve in West Palm Beach. Single-family homes remain in seller's territory, while condos have tipped toward buyers, creating divergent conditions within the same zip codes.
Jacques points to supply and speed as key indicators. Single-family homes carry roughly 3.5 months of supply, a level associated with a seller's market, while condos sit closer to 6.7 months. The median single-family home goes under contract in about 40 days, compared with about 69 for condos, and single-family homes typically close near 95 percent of their original list price, against roughly 93 percent for condos. That extra month on the market carries weight, as each additional week tends to invite lower offers. Multiple offers still occur on well-priced houses but are uncommon on condos unless the building is newer or fully funded. Despite the slowdown, condo prices have not collapsed; Jacques puts the median condo price up about 5 percent year over year.
Much of the pressure on older condos traces to reforms Florida adopted after the 2021 Surfside collapse. For years, associations could choose not to fund reserves, and many did. Buildings three stories or taller must now complete a Structural Integrity Reserve Study and set money aside for the repairs it identifies. "Owners in older buildings are now paying for decades of delayed repairs all at once," Jacques says. That cost arrives as higher monthly dues, special assessments, or both. Financing has tightened alongside it. Jacques estimates that only about 21 of roughly 2,400 South Florida condo buildings are approved for FHA loans, and more than half of condo purchases in Palm Beach County are now paid in cash.
The single-family side faces the opposite problem. Many owners holding low-rate mortgages are staying put, and Jacques estimates the county has about 24 percent fewer single-family homes available than a year ago. Buyer preference is shifting too, toward owning land without association rules and toward simpler financing. That does not make it 2021 again. Buyers remain price-sensitive, and homes that are priced in line with the market tend to move quickly while those that are not can sit.
The county-wide condo figure can mislead. A headline showing condo prices up 5 percent blends newer, well-funded buildings with older ones that may be flat or declining. For an individual unit, Jacques says, the building's reserve study and financial health matter more to price than the county median does. That makes the buyer's side of the process increasingly about documents rather than square footage.
The county's housing story heading into the fall is less about direction than divergence. Single-family homes are being priced against a shortage. Condos, as Jacques puts it, "are a building-by-building decision." For buyers, sellers, and agents, the implications are clear: strategies must be tailored to each segment, with condo transactions demanding greater scrutiny of building finances and single-family deals requiring swift action amid tight inventory. This divergence is likely to persist as long as inventory constraints and post-Surfside regulations remain in place.